Impact Beyond Numbers: Social Media Benchmarks for Brands in Ukraine
The Ukrainian advertising market is increasingly shifting toward digital platforms and formats. For three consecutive years, alongside traditional media and digital tools, investments in SMM and influencer marketing have continued to grow. At the same time, as budgets increase, a key question becomes more relevant: how do we understand whether these investments are working? How can we measure the impact of content that cannot be reduced to conventional media metrics such as reach and frequency?
Publicis Groupe Ukraine, together with YouScan, conducted an extensive analysis of Social Listening data across eight categories over more than two years to establish the first Ukrainian social media benchmarks and show brands how to work systematically with relevant SMM metrics.
SMM and Influencer Marketing: Three Years of Sustained Investment Growth
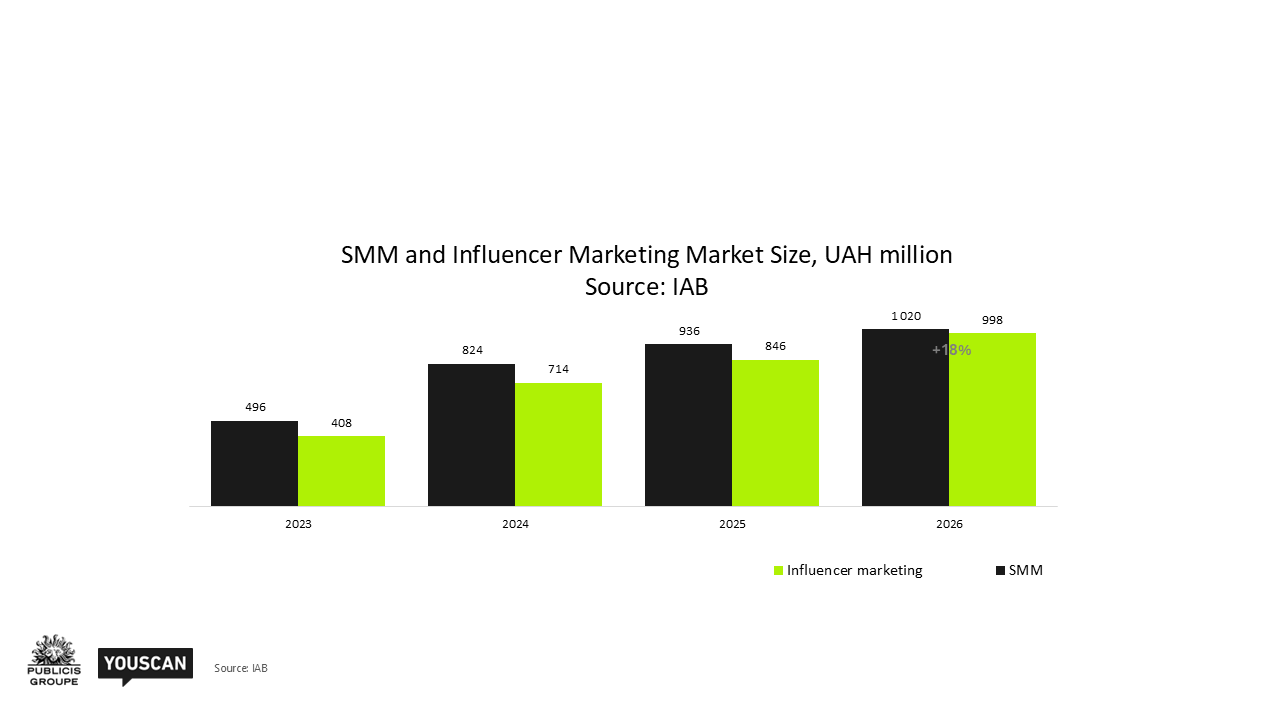
Social media is a segment that continues to scale confidently. According to IAB data, in 2023, UAH 408 million was invested in SMM in Ukraine, while influencer marketing attracted UAH 496 million. Since then, the trend has remained strongly positive, with investment projected to double by 2026 compared with 2023.
This means brands are actively shifting budgets to digital touchpoints where consumers spend the most time — spaces where brands can not only remind people about themselves but also actively engage audiences.
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
However, as spending increases, brands face three systemic questions that virtually every client asks an agency:
- ROI. How can we measure the contribution of social media to business outcomes — sales, loyalty, and brand awareness?
- Creative. What content actually works, and what goes unnoticed despite investment in production? And how important a role does creativity play overall?
- Relevance. Which platforms, volumes, and formats make sense specifically for our category?
Without market benchmarks, it is almost impossible to answer these questions objectively. That is why we set out to create a systematic market view. And we started with the metrics captured through Social Listening.
Working with Social Listening data involves three structural barriers that make it difficult to establish market standards:
- Unstructured data. Social media mentions are “raw” content: texts, videos, comments, reactions, stickers. Standardizing them across platforms is more difficult than working with traditional media impressions.
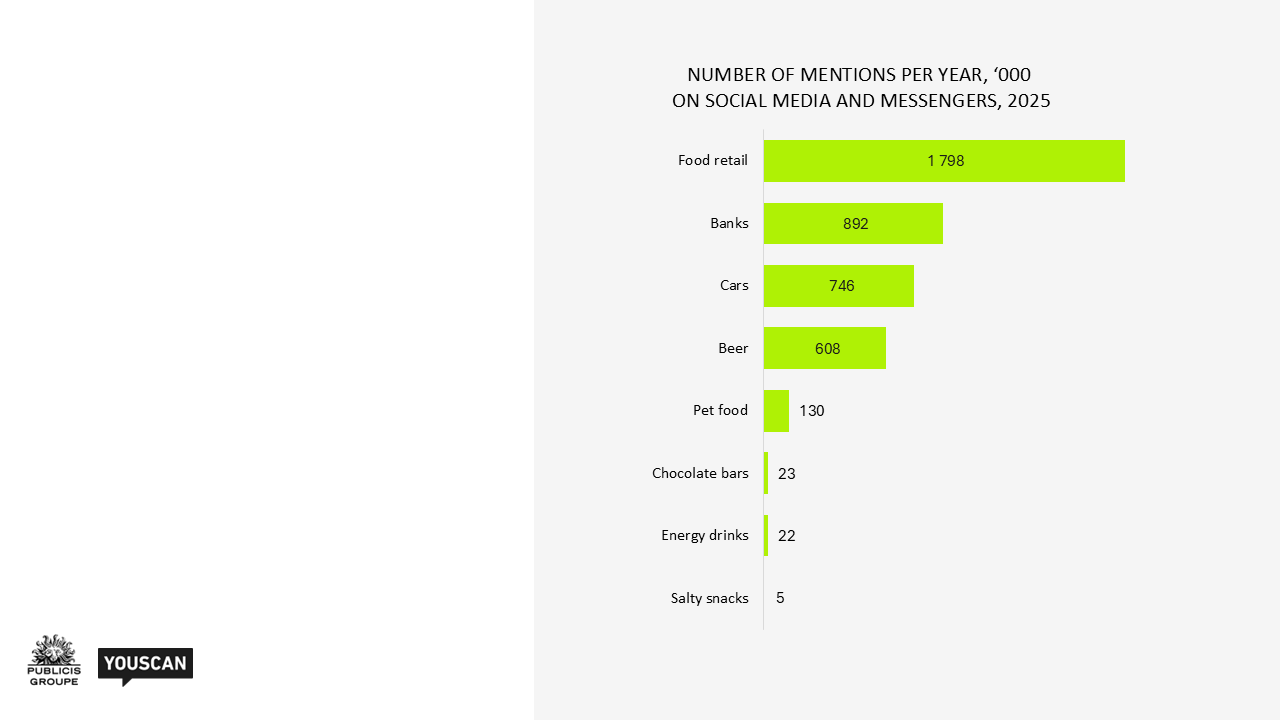
- Volume. The “food retail” category alone generates 1.8 million mentions a year. It is impossible to handle such volumes manually — automated monitoring and classification tools are required.
- Measurement complexity. A direct correlation between a “mention → purchase” is rare. Brands have to work with proxy metrics (Word of Mouth (WOM), Engagement Rate (ER), sentiment). That is why having benchmarks for these metrics is critical.
How Millions of Mentions Become Data and Insights
The data for this study was collected and analyzed using YouScan — a platform for monitoring mentions across social media and online media. Before moving to the results, it is worth looking at how a dataset of this scale can be transformed into a structure suitable for comparison and benchmark development.
Social media mentions are highly noisy: commercial posts, irrelevant comments, and spam clutter the dataset. Not every mention is useful for analysis either. That is why automated categorization is essential: YouScan highlights commercial mentions, promotional and advertising posts, spam, and posts unrelated to the search query. At the same time, it identifies what is relevant to brands. First and foremost, this includes WOM: user mentions, reviews, recommendations, and comparisons — everything related to brands, products, and services that is published by real users.
An online mention can no longer be reduced to text alone. Increasingly, brands appear visually in content without being named in the caption: a product photo on a store shelf, an unboxing shot, a video review. Sometimes the mention exists only in audio. Traditional text search misses such mentions, creating a blind spot: part of the conversation about a brand remains unseen. Analyzing images, video, and audio brings this content back into view, and only then does the category picture become complete.
For each mention, sentiment, source type, topic, positive and negative attributes, and information about the author (including demographic characteristics and even hobbies and interests) are determined automatically. When dealing with millions of mentions, manual coding is physically impossible, so automated classification and tagging become essential.
Finally, there is consistency in how benchmarks are built and measured. A single number means nothing on its own. The answer emerges only when a metric is calculated consistently across all categories, platforms, and periods — while accounting for the specifics of each platform and news events that may distort the count while remaining irrelevant to the category. This consistency turns a set of indicators into a benchmark: a common reference point against which each brand can interpret its own numbers.
Methodology: 8 Categories × 8 Platforms × 27 Months
Instead of analyzing a single case, we chose the broadest possible scope: 8 categories × 8 platforms × 27 months of data.
The study covers eight different consumer categories with different purchasing behaviors — from everyday FMCG to high-involvement purchases, from mass retail to niche segments:
- Food retail
- Banks
- Automobiles
- Beer
- Pet food
- Chocolate bars
- Energy drinks
- Salty snacks
The analysis covers eight key social platforms: TikTok, Threads, Instagram, YouTube, Facebook, Telegram, X (Twitter), and Pinterest. The period covered is January 1, 2024 to March 31, 2026.
Volume of Mentions: Stability with Very Different Internal Dynamics
At an aggregate level, the market shows confident but moderate growth: 4.06 million mentions were recorded across the eight categories in 2024, compared with 4.22 million in 2025 (+4% year over year). In Q1 2026, the volume of mentions increased by a modest 0.8% compared with Q1 2025 (333.2 thousand versus 330.5 thousand mentions). But the “average temperature” conceals sharply diverging trends within individual categories.
- Food retail — the most actively discussed category (1,798 thousand social media mentions in 2025).
- Banks ranked second, with roughly half as many mentions (892 thousand). It is worth noting that we deliberately excluded mentions of Monobank from this category because its communication approach differs from other banks and it is also frequently mentioned in connection with fundraising. Including it would have distorted the category-wide picture.
- Chocolate bars and energy drinks are discussed much less actively (23 thousand mentions).
- Salty snacks are the least active of the analyzed categories (5 thousand mentions).
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
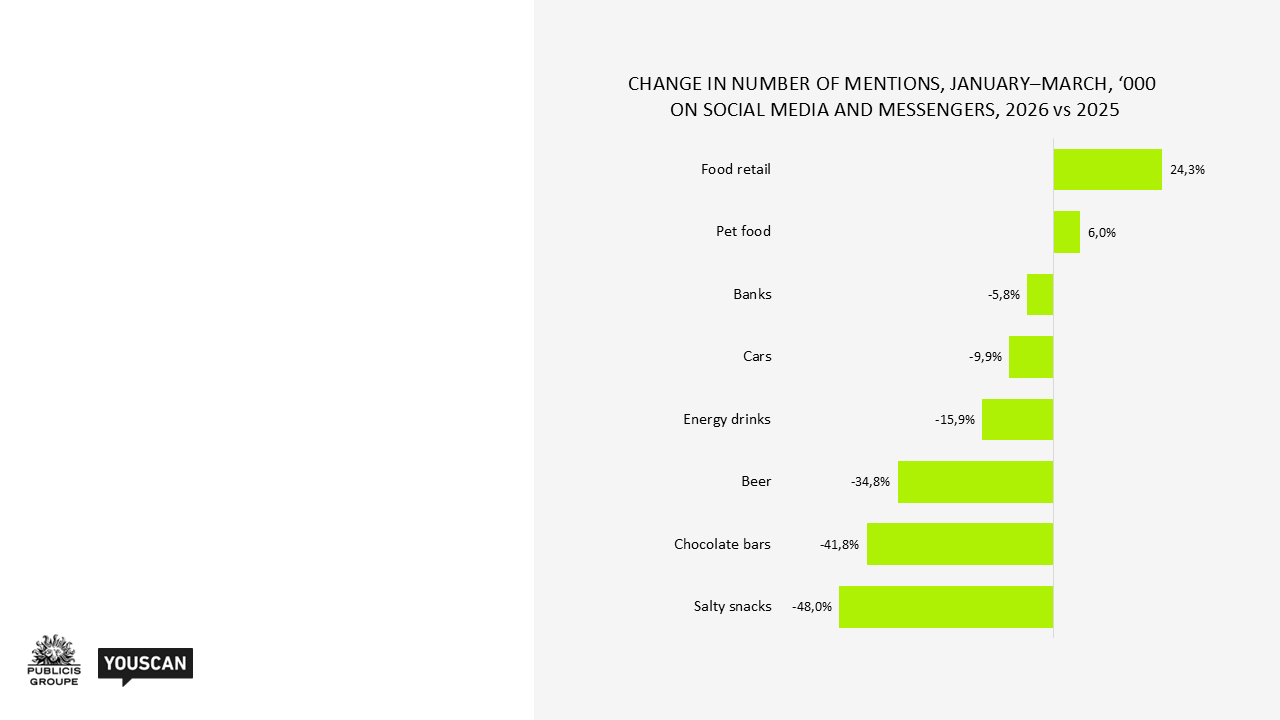
The Q1 2026 vs. Q1 2025 dynamics show an even sharper divergence:
- Food retail and pet food are growing in terms of mention volume.
- Banks and automobiles are showing a slight decline compared with 2025.
- The remaining categories demonstrate a significant decline.
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
What does this mean for brands? The category sets the “entry threshold” — the level of activity that is critically necessary to be visible. In growing categories, this threshold rises every year, meaning campaigns with insufficient activity risk getting lost. In stagnant or declining segments, by contrast, even lower levels of activity create more opportunities to attract attention.
WOM: The User Voice Matters More Than the Brand Voice
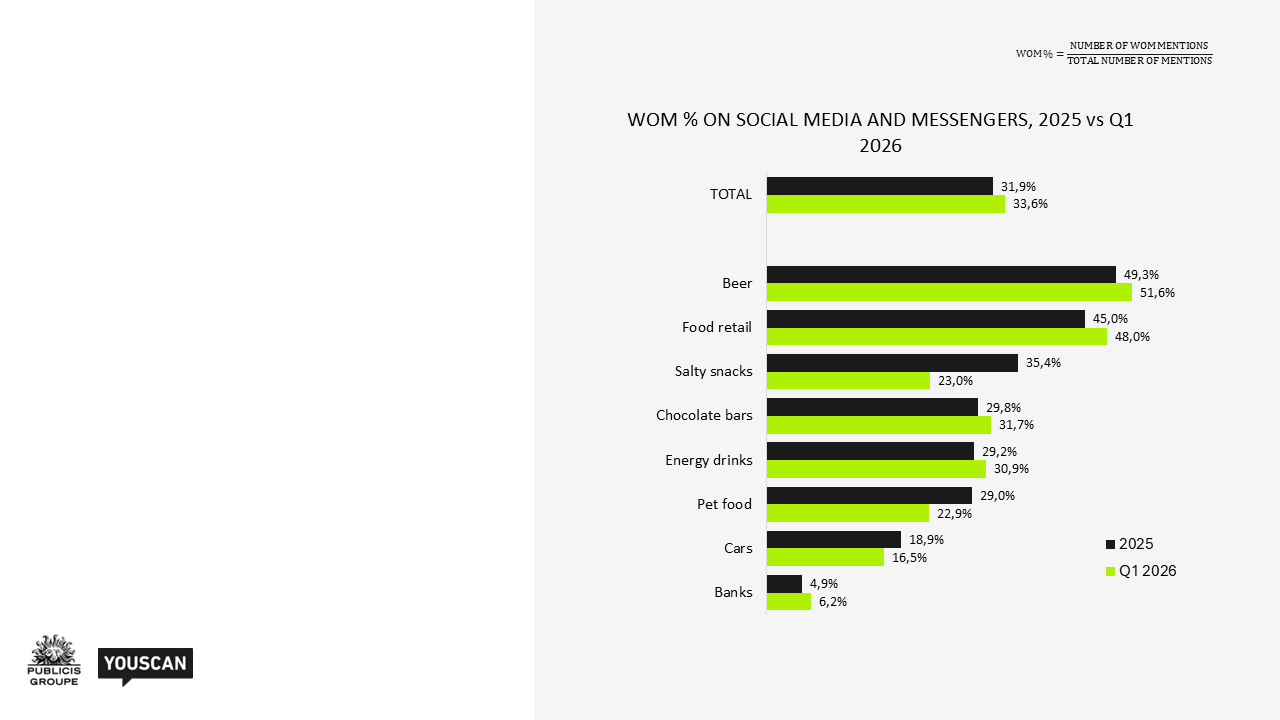
One of the key findings of the study is that, on average, more than one-third of all social media mentions are generated by users themselves (WOM), rather than brands or influencers: 37.7% in 2024, 31.9% in 2025, and 33.2% in Q1 2026. In other words, a brand that does not analyze UGC remains “blind” to one-third of the signals in its category.
The distribution of WOM also varies significantly by category — different categories stimulate different levels of user activity.
- Beer is the category with the largest stable share of UGC (49.3% in 2025 and 51.6% in Q1 2026).
- Food retail has almost the same share of WOM (45.0% in 2025), which the category recovered to its 2024 level (48%) at the beginning of 2026.
- Salty snacks have been losing share of conversation for the second year in a row, declining from 35.4% in 2025 to 23.0% in Q1 2026.
- Chocolate bars have been growing steadily year over year and in Q1 2026 had almost one-third of mentions coming specifically from UGC.
- Energy drinks had the highest WOM share in 2024 (~70%) thanks to active promotions and cooperation with S.T.A.L.K.E.R. After declining in 2025, the category is gradually recovering its WOM share.
- Banks have the lowest WOM share — just 4.9% in 2025 and 6.2% in Q1 2026 (the category excludes Monobank).
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
Compared with 2024, the total number of WOM mentions declined by approximately 12% in 2025. However, in Q1 2026 we are already seeing a reversal: WOM is returning (+11% versus Q1 2025). Audiences are ready for “live” conversations, and brands that invest in content that encourages participation gain a powerful lever for influence.
Engagement Rate: Engagement Is Growing, but Unevenly
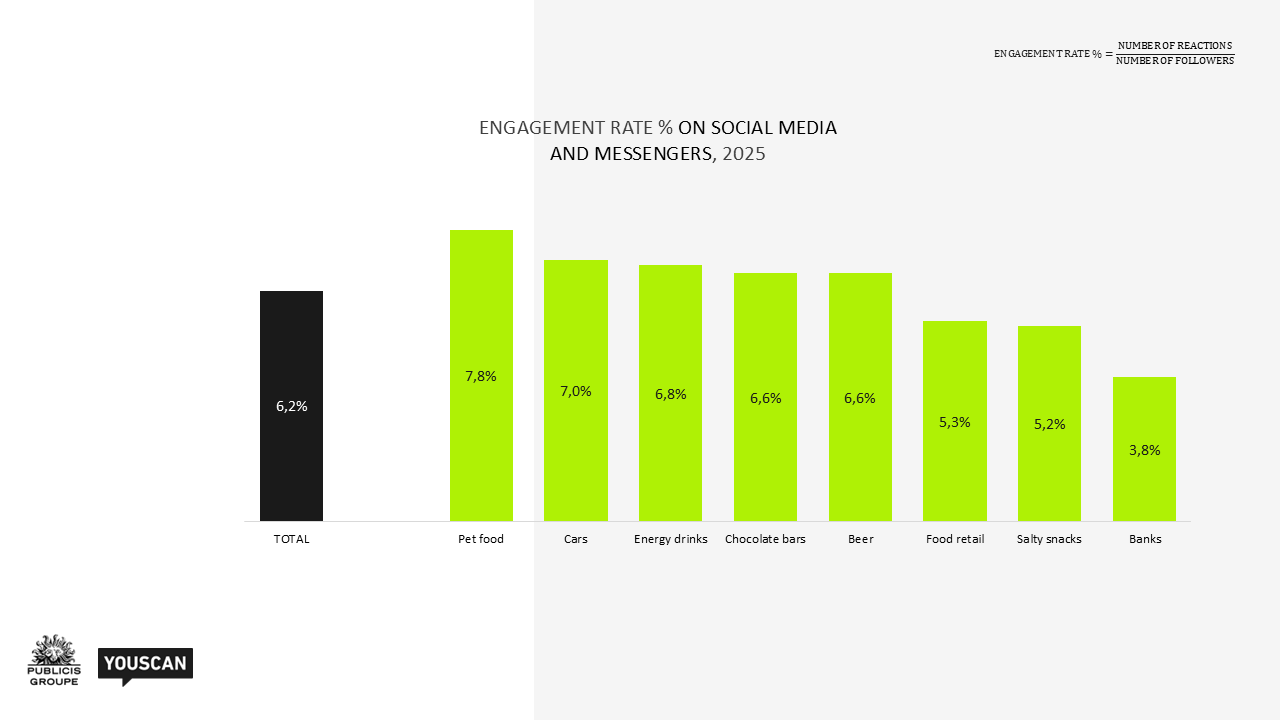
Average Engagement Rate (the ratio of likes, shares, and comments to the number of followers) across the eight categories is also increasing year over year. In 2024, Total ER was 5.2%, while WOM ER was 6.7%. In 2025, these figures reached 6.2% and 6.9%, respectively. A universal pattern can be observed: user-generated content receives more engagement than branded content. This is confirmed in 7 out of 8 categories.
ER by category in 2025 (total):
- Pet food — the category with the highest engagement (7.8%). This is quite expected for an emotional category that frequently uses images of animals in its communications. Animals and children tend to generate the strongest positive response.
- Automobiles — 7.0%.
- Energy drinks — 6.8%.
- Chocolate bars — 6.6%. This is the category with the largest gap between UGC engagement and engagement with branded content.
- Beer — also 6.6%. Although it is the most discussed category, conversion into reactions is around the average level here.
- Food retail shows a similar pattern: despite high discussion volume, ER is even below average (5.3%).
- Salty snacks increased to 5.2% from 3.3% in 2024. Promotional activations designed to generate standard baseline UGC work well for increasing the number of mentions, but not for generating an emotional response to this content.
- Banks have the lowest ER (3.8%). The explanation is simple: banking communication is perceived primarily as an expert source of information (exchange rates, products, security), so it does not trigger a strong emotional response. At the same time, banks are the only category where users react to official posts at the same level as to UGC (ER for branded and user-generated content is practically identical).
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
For brands, this is a clear signal: if your branded ER is significantly lower than the category’s WOM ER, you are losing the battle for attention.
These results also confirm that:
- Working with micro-influencers can deliver higher engagement than branded content or partnerships with large creators.
- UGC should be a source of insights and inspiration for increasing audience engagement with brand communications.
Platforms: TikTok and Threads Gain, Telegram and Pinterest Lose
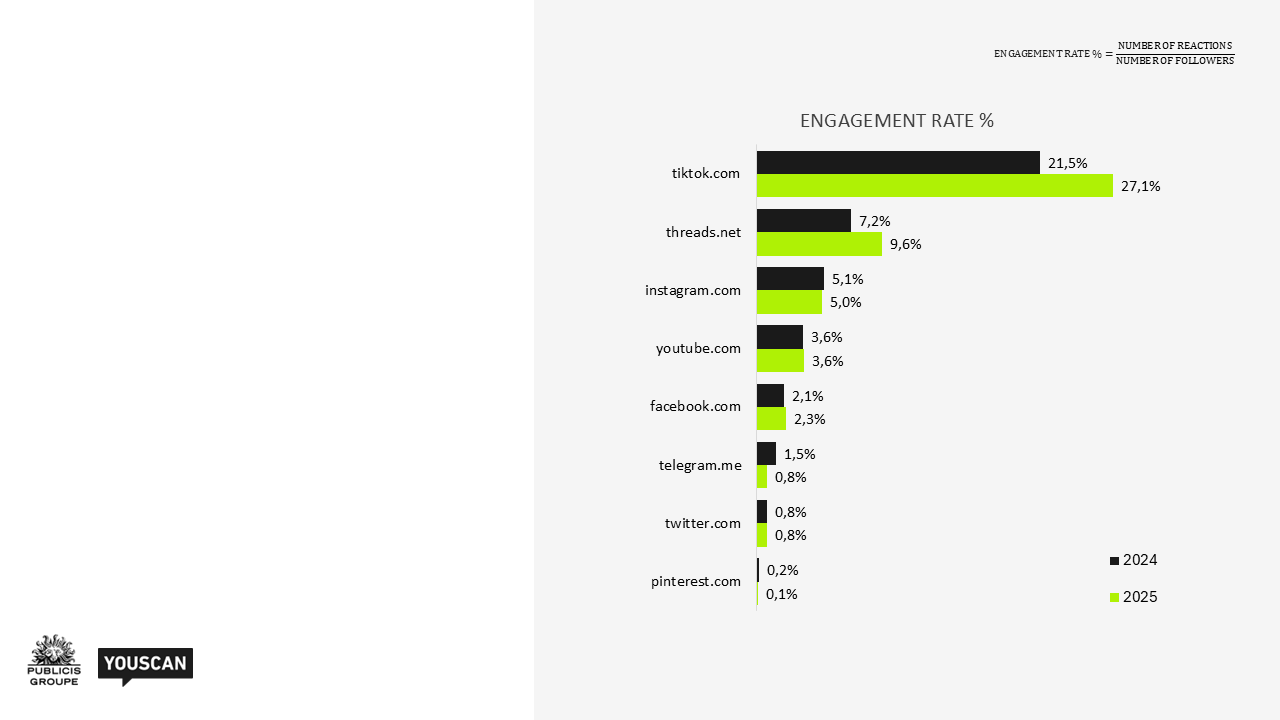
The distribution of activity across platforms is changing faster than any other indicator. The platform-level ER dynamics from 2024 to 2025 confirm the global shift toward video formats and microblogging:
- TikTok (+5.6 pp) and Threads (+2.4 pp) show the largest growth. These networks also have the highest ER overall. Their growing share of the activity mix is one of the factors behind the overall improvement in ER across the analyzed pool of categories.
- Instagram, YouTube, and X (Twitter) remain stable. Facebook also has an almost unchanged ER level, with a slight increase.
- By contrast, Telegram’s ER has fallen by almost half.
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
For brands, this means the platform mix needs to be reconsidered: being “a little bit everywhere” is becoming inefficient. Media strategy should take into account not only reach, but also a platform’s ability to generate a meaningful response to a specific type of content. During the analysis, we also observed some variation in platform ER by category. Therefore, it is important to consider not only overall benchmarks, but also the fit between the platform, your audience, and your content.
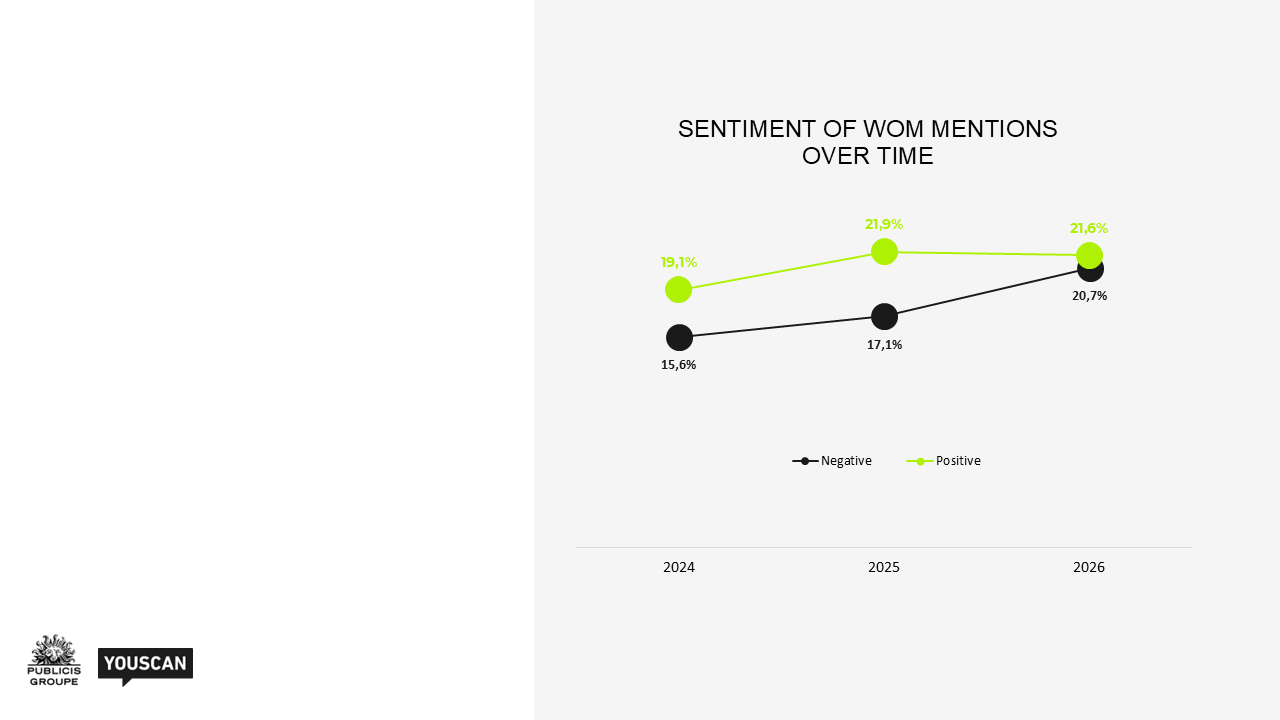
Sentiment: Negative Mentions Are Rising, but Positive Sentiment Still Prevails
One of the most concerning trends in the study is the gradual increase in the share of negative mentions: 15.6% in 2024 → 17.7% in 2025 → 20.7% in Q1 2026. At the same time, positive sentiment remains high: 19.1% → 21.9% → 21.6%. In other words, audiences are becoming more emotionally polarized in both directions, while the share of neutral mentions is declining.
- Ukrainians are becoming increasingly sensitive in conditions of constant stress.
- In the media environment, content that triggers an emotional response performs better.
 Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
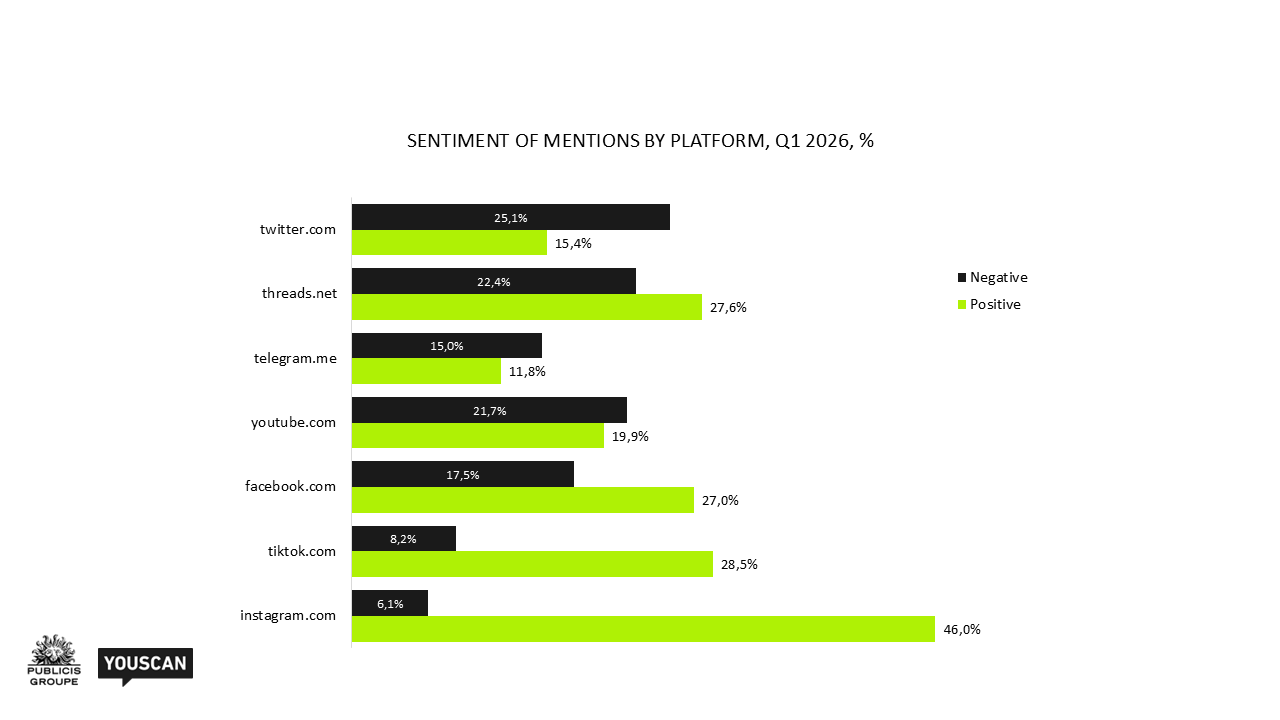
In Q1 2026, sentiment is unevenly distributed across platforms.
- X (Twitter) consistently remains a “hate platform” (25.1% negative sentiment).
- Threads ranks second for negative sentiment (22.4%), while at the same time showing a growing share of positive sentiment (27.6%). This supports the platform’s positioning as the most open, honest, and transparent in communication — and therefore one of the most emotionally expressive.
- Instagram and TikTok remain predominantly positive. Instagram has the highest share of positive sentiment (46%). TikTok shows confident growth, from 18.7% in 2025 to 28.5% in Q1 2026. It is therefore unsurprising that these two networks often “save” Ukrainians and take up an increasing share of their media consumption time.
Source: YouScan Social Listening for the Auto, Beer, Chocolate Bars, Energy Drinks, Food Retail, Pet Food, Banking, and Salty Snacks categories, 01/01/2024–03/31/2026. Social media and messaging platforms: facebook.com, telegram.me, twitter.com, tiktok.com, youtube.com, instagram.com, threads.net.
Practical takeaway: sentiment monitoring should be platform-specific. The same news event can trigger diametrically opposite reactions on Facebook and TikTok.
4 Key Insights for Brands
1. Category Activity Sets the “Entry Threshold”
Before setting targets for mention volume or ER, compare your metrics with category benchmarks. In growing categories, the “ceiling” for communication needs to be raised every year; otherwise, you will systematically lose share of voice. In stagnant or declining segments, by contrast, a window opens for rapid SOV growth.
2. Brand Campaigns Have a Noticeable Impact on Activity and Engagement
Peaks in brand activity on social media clearly coincide with periods of active campaigns. Social Listening data can be used as a rapid tactical barometer of creative and brand performance — alongside a traditional post-buy analysis.
3. UGC Drives Stronger Engagement, but It Depends on the Category
In 7 out of 8 categories, WOM ER is higher than branded ER. This is a strong argument for investing in user-generated content, referral programs, and influencer collaborations, where the user voice is a key driver of engagement. Consumer mentions can also be a source of insights and inspiration for branded content.
4. Platform Choice Directly Affects ER
The difference in Engagement Rate between platforms is substantial: 27.1% on TikTok versus 0.8% on Telegram and X (Twitter). This means that with the same budgets and creative, engagement metrics can differ by multiples simply because of the choice of platform.
Conclusion: Benchmarks Are the New Starting Point for Social Media Brand Strategies
Our research shows that there are no “universally good” numbers in social media. A metric that is strong for banks may be average in the pet food category, and vice versa. Therefore, building your own benchmarks — category-specific, platform-specific, and updated quarterly — should become an important element of SMM and influencer strategy planning.
At Publicis Groupe Ukraine, we are continuing to expand this benchmark database together with YouScan and will be happy to share new findings and updates with the market.
The next logical step is to integrate Social Listening data with brand business metrics (sales, brand health tracking, conversion) using Marketing Mix Modeling and to create custom dashboards. This is when social media metrics will begin to systematically demonstrate their business value.
Source: YouScan Social Listening; Data Science analysis by Publicis Groupe Ukraine. 8 categories (food retail, banks, automobiles, beer, pet food, chocolate bars, energy drinks, salty snacks), 8 platforms (TikTok, Threads, Instagram, YouTube, Facebook, Telegram, X (Twitter), Pinterest), period 01/01/2024–03/31/2026.